A new heat pump or air conditioning system is one of the largest home purchases a Las Vegas homeowner makes. Costs typically run between $5,000 and $15,000 depending on the system type, efficiency rating, and installation complexity. For many households, paying that amount out of pocket isn’t realistic — especially when the system fails unexpectedly in the middle of summer and there’s no time to save up. HVAC financing makes it possible to move forward with the right system for your home without waiting, without draining savings, and without settling for a cheaper option that costs more to operate in the long run. At Doctor Heat Pump, we want every Las Vegas homeowner to understand their financing options before they need them — not after a system failure forces a rushed decision.
This guide covers how HVAC financing works, what options are available in the Las Vegas market, what to watch out for, and how financing interacts with available tax credits and rebates.
Why HVAC Financing Makes Sense in Las Vegas
Las Vegas homeowners have a specific financial case for HVAC financing that goes beyond simple convenience.
Systems fail at the worst possible time. A heat pump or AC that fails in July doesn’t give you weeks to save up. It gives you days — sometimes hours — before indoor temperatures become dangerous. Financing provides immediate access to a replacement without the timeline pressure of an emergency forcing a compromise on system quality or efficiency.
Higher efficiency saves money over time. The difference between a 15 SEER2 system and a 20 SEER2 system can be $3,000 to $5,000 upfront. In Las Vegas, where systems run heavily for six to seven months per year, that efficiency difference translates to $400 to $600 in annual energy savings. Financing the premium allows you to choose the system with the better long-term economics — and the energy savings help offset the monthly payment.
Las Vegas electricity rates make efficiency a financial priority. NV Energy rates and Las Vegas’s extreme cooling demand make HVAC one of the largest line items in a household energy budget. A higher-efficiency system financed at a reasonable rate often costs less per month — combined payment plus reduced energy bill — than a cheaper system paid in cash.
HVAC Financing Options Available in Las Vegas
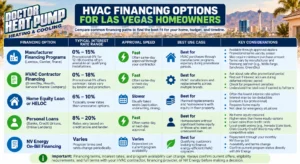
Several financing paths are available to Las Vegas homeowners. Each has different terms, eligibility requirements, and cost structures.
Manufacturer Financing Programs
Most major HVAC manufacturers — Lennox, Carrier, Trane — offer financing programs through their dealer networks. These programs are often the most accessible option because they’re specifically designed for HVAC purchases and available directly through the installing contractor.
Lennox financing is available through approved Lennox dealers and periodically offers promotional terms — including zero interest for 12 to 18 months on qualifying installations. These promotions typically run during slower seasons and may require a minimum purchase amount. Ask about current Lennox financing offers at the time of your installation consultation.
Carrier and Trane offer similar dealer-based financing programs with comparable promotional structures. Terms vary by promotion and by the financing partner each manufacturer uses — Wells Fargo, Synchrony, and GreenSky are common partners for major HVAC manufacturers.
The key advantage of manufacturer financing is accessibility — approval is often faster and more flexible than traditional bank financing, and the contractor handles most of the paperwork.
HVAC Contractor Financing
Many Las Vegas HVAC companies offer financing directly through third-party financing partners — GreenSky, Hearth, and Service Finance Company are common in the HVAC industry. These programs work similarly to manufacturer financing but may be available across brands rather than tied to a specific manufacturer’s product line.
When evaluating contractor financing, ask specifically about:
- The interest rate after any promotional period ends
- Whether interest accrues during a deferred-interest period
- Prepayment penalties
- The total cost of financing if carried to the full term
Home Equity Loan or HELOC
For Las Vegas homeowners with equity in their property, a home equity loan or home equity line of credit (HELOC) often offers the lowest interest rate available for an HVAC purchase. Interest on home equity financing may also be tax-deductible depending on your tax situation — consult a tax professional for guidance specific to your circumstances.
The trade-off is time. Home equity financing requires an application process that takes weeks, not days. It’s a better option for planned replacements than emergency situations.
Personal Loans
Personal loans from banks, credit unions, or online lenders are available without collateral and can sometimes be approved quickly. Interest rates are typically higher than home equity financing but lower than credit cards. For Las Vegas homeowners without significant home equity, a personal loan from a credit union — Nevada State Bank, Clark County Credit Union, or similar — may offer competitive rates.
NV Energy On-Bill Financing
NV Energy has periodically offered on-bill financing programs that allow qualifying customers to finance energy-efficient HVAC upgrades and repay through their monthly utility bill. Availability and terms change — confirm current program status directly with NV Energy before counting on this option.
What to Watch Out For: Deferred Interest vs. True Zero Interest
This distinction matters more than almost anything else in HVAC financing — and it catches many homeowners off guard.
True zero interest means no interest accrues during the promotional period. If you pay off the balance before the period ends, you pay exactly the purchase price. If you carry a balance after the period, interest begins accruing on the remaining balance going forward.
Deferred interest means interest accrues during the promotional period but is waived if you pay the balance in full before it ends. If you carry any balance at the end of the promotional period — even $1 — all of the accrued interest is added to your balance immediately. On a $10,000 installation at 26.99% APR, 18 months of deferred interest can add $3,500 or more to your balance in a single day.
Many HVAC financing promotional offers use deferred interest rather than true zero interest. Always ask specifically which structure applies before signing. If the offer is deferred interest, either pay the balance before the promotional period ends or treat the stated interest rate as the effective rate from day one.
How HVAC Financing Interacts With Tax Credits and Rebates
Financing a qualifying heat pump installation doesn’t reduce your eligibility for available incentives — and stacking them meaningfully changes the effective cost of the purchase.
Federal heat pump tax credit
Qualifying heat pump installations are eligible for a federal tax credit of 30% of the installed cost, capped at $2,000. This credit applies to the full installed cost regardless of how much you finance. If you finance a $10,000 installation and claim a $2,000 tax credit, your effective financed amount is $8,000 — reducing both your monthly payment and the total interest cost.
NV Energy rebates
NV Energy periodically offers rebates on qualifying high-efficiency equipment. These rebates are typically paid after installation and can be applied toward the financed balance, further reducing the amount you carry.
Manufacturer rebates
Seasonal manufacturer rebates from Lennox, Carrier, and Trane can be stacked with financing, tax credits, and utility rebates simultaneously. Ask your contractor what rebates are currently available at the time of purchase.
Here’s how the math can look on a real installation:
| Item | Amount |
|---|---|
| Lennox XP21 full system — installed cost | $10,500 |
| Lennox manufacturer rebate | -$200 |
| NV Energy rebate (estimated) | -$300 |
| Amount financed | $10,000 |
| Federal tax credit (applied at tax time) | -$2,000 |
| Effective net cost after tax credit | $8,000 |
That $8,000 spread over 18 months of zero-interest financing is approximately $444 per month — before factoring in the monthly energy savings from a more efficient system. For more on how the federal credit works, see our guide on the federal heat pump tax credit in 2026.
Questions to Ask Before Signing a Financing Agreement
Before signing any HVAC financing agreement, get clear answers to these questions:
- Is this true zero interest or deferred interest?
- What is the interest rate after the promotional period ends?
- What is the minimum monthly payment during the promotional period?
- Is there a prepayment penalty if I pay the balance early?
- What happens if I miss a payment during the promotional period?
- Is there an origination fee or other upfront cost?
- Can I apply a tax credit or rebate payment toward the balance mid-term?
A reputable contractor and a reputable financing partner answer all of these questions clearly and in writing before you sign. Pressure to decide quickly without reviewing terms is a red flag.
Financing for Emergency Replacements vs. Planned Upgrades
The right financing approach differs depending on whether you’re replacing a failed system under time pressure or planning ahead.
Emergency replacement: Manufacturer or contractor financing is usually the fastest path. Applications can often be completed and approved the same day, allowing installation to proceed immediately. In this situation, the priority is speed — and the terms available on short notice may not be the most favorable. If possible, have a financing option identified before an emergency occurs rather than evaluating options under pressure.
Planned upgrade: A planned replacement gives you time to compare financing options, negotiate terms, and potentially use home equity financing at a lower rate. It also gives you time to time the purchase around a promotional financing offer or a manufacturer rebate period — which can significantly improve the total cost of the upgrade.
Why Las Vegas Homeowners Choose Doctor Heat Pump
Doctor Heat Pump is a local, family-owned HVAC company serving Las Vegas, Henderson, and North Las Vegas. We specialize in heat pump installation, heat pump replacement, and service across the Las Vegas Valley.
When you work with Doctor Heat Pump, we walk you through available financing options alongside the system recommendations — so you can make a decision that makes sense for your home and your budget.
Frequently Asked Questions
Does financing a heat pump affect my tax credit eligibility?
No. The federal heat pump tax credit applies to the full installed cost of a qualifying system regardless of how much you finance. The credit is based on what you paid for the installation, not on how you paid for it.
What credit score do I need for HVAC financing?
Requirements vary by financing partner. Many manufacturer and contractor financing programs approve applicants with credit scores in the 620 to 640 range, though better terms are available at higher scores. Some programs offer no-credit-check options with different term structures. Ask your contractor about options if credit is a concern.
Can I finance just part of the cost and pay the rest in cash?
Yes — most financing programs allow you to finance any amount up to the total installation cost. Financing a portion while paying the rest in cash reduces your monthly payment and total interest cost while still preserving access to immediate installation.
How quickly can HVAC financing be approved in Las Vegas?
Manufacturer and contractor financing programs can typically be approved within minutes to a few hours through an online application. Bank or credit union personal loans typically take one to three business days. Home equity financing takes several weeks.
Is HVAC financing worth it if I can pay cash?
Potentially yes — especially if a promotional zero-interest offer is available. If you can invest the cash at a return higher than the financing rate, financing the purchase and keeping your cash invested is a rational financial decision. It also preserves your cash reserves for other expenses or emergencies.
Ready to Explore HVAC Financing Options?
A new heat pump or AC system is a significant investment — and the right financing makes it accessible without compromising on the system your home actually needs. Understanding your options before you need them puts you in a much stronger position when the time comes to make a decision.
Doctor Heat Pump is here to help Las Vegas, Henderson, and North Las Vegas homeowners find the right system and the right financing to go with it. Call us at 702-467-7236 or contact us online to discuss your options. We’ll give you honest information and let you make the decision that’s right for your budget.
References
-
- U.S. Department of Energy — Financing Energy Efficiency Upgrades
- ENERGY STAR — Financing and Incentives for Heat Pumps